Last Update – 23-10-2026
Choosing the best cash back credit card in UAE can make everyday spending more rewarding, particularly for residents who regularly pay for groceries, fuel, restaurants, school fees and online purchases.
Several UAE banks advertise cashback rates of 5%, 8%, 10% or even 35%. However, these percentages rarely apply to every purchase.
A card offering 10% cashback may impose a monthly spending threshold, restrict eligible transactions or limit the actual reward to AED 150–300 per category.
For example, someone spending AED 5,000 monthly could benefit more from a card returning a consistent 2% than from a premium card advertising 10% cashback but imposing conditions they cannot meet.
We compared published cashback structures, annual charges, eligibility requirements and redemption conditions across traditional banks, Islamic banks and digital banking providers.
Our shortlist of 15 cards considers practical value rather than simply ranking the highest advertised percentages.
Rates and offers were checked against available issuer information in October 2026. They may change, and approval is always subject to the issuing bank’s assessment.
What Are the 15 Best Cash Back Credit Cards in UAE?
The comparison below highlights the strongest features of the 15 shortlisted options.
| Credit Card | Advertised Cashback | Annual Fee | Minimum Monthly Salary |
| ADCB 365 Cashback | Up to 6% | Free first year; AED 383.25 thereafter | AED 5,000 |
| Mashreq Cashback | Up to 5% | Free for life | AED 5,000 |
| HSBC Live+ | Up to 6% | Free first year; AED 313.95 thereafter, waivable | From AED 5,000 |
| SIB Cashback | Up to 10% | Free first year; AED 199 thereafter, waivable | AED 5,000–8,000 |
| Citi Cash Back | Up to 3% | Free first year; subsequent fee waivable | AED 8,000 |
| FAB Cashback | Up to 5% | AED 300, before applicable VAT | AED 5,000 |
| CBD Super Saver | Up to 10% | Free first year; subsequent fee applies | AED 5,000 |
| Emirates Islamic Switch | Up to 8% | Free first year; subsequent fee waivable | AED 5,000 |
| DIB Consumer Cashback Platinum | Up to 4% | AED 249 plus VAT; first-year promotion available | AED 15,000 |
| Dubai First Cashback | Up to 5% | First year free; subsequent charges apply | AED 5,000 |
| Wio Credit | Up to 2% | Depends on banking plan | Subject to eligibility |
| Liv Cashback | Up to 2% | Free for life | AED 5,000 |
| RAKBANK Titanium | Up to 5% on essentials | Free for life | AED 8,000 |
| Al Hilal Cashback | Up to 5% | Free for life | Typically AED 5,000 |
| ADCB Talabat | Up to 35% as Talabat credit | Free for life | AED 5,000 |
The percentages above are maximum advertised category rates, not guaranteed returns across all spending.
1. ADCB 365 Cashback Credit Card – Best for Everyday Household Spending
The ADCB 365 Cashback Credit Card is a strong all-round choice for households that spend regularly on dining, groceries, transport and digital subscriptions.
Its rewards structure combines several common spending categories instead of concentrating exclusively on shopping or travel.
ADCB currently advertises 6% cashback on dining, 5% on fuel and Salik, and 3% on groceries. Eligible home entertainment and AI-powered subscriptions can also earn 5%.
The important condition is the minimum monthly retail spend of AED 5,000. Customers spending below this amount do not qualify for the advertised cashback rewards.
| Feature | Details |
| Dining cashback | 6% |
| Fuel and Salik | 5% |
| Groceries | 3% |
| Selected digital subscriptions | 5% |
| Other eligible spending | Up to 1% |
| Maximum monthly cashback | AED 1,000 |
| Minimum monthly spend | AED 5,000 |
| Annual fee | Free first year; AED 383.25 thereafter |
| Minimum salary | AED 5,000 or qualifying credit eligibility |
For a family already spending AED 5,000 or more each month, the combination of rewards could be valuable.
However, a smaller household spending AED 3,000 monthly would be better served by a card without such a high qualifying threshold.
The card also advertises a welcome bonus, subject to separate transaction and spending conditions.
Our assessment: Particularly competitive for established households with predictable monthly expenses above AED 5,000. The main limitation is the spending floor, not the cashback cap.
2. Mashreq Cashback Credit Card – Best Free-for-Life Dining Card
The Mashreq Cashback Credit Card is one of the more accessible options for residents seeking rewards without an annual membership fee.
The card earns 5% on eligible local and international dining transactions.
Other international purchases currently earn 1%, while eligible local retail transactions earn up to 1%. Government payments, education, telecom, utilities, fuel and certain other categories receive a lower 0.15% rate.
Unlike many competing products, Mashreq does not require a minimum monthly spend to begin earning cashback.
| Feature | Details |
| Dining | 5% |
| Other international spending | 1% |
| Other eligible local retail | Up to 1% |
| Selected lower-rate categories | 0.15% |
| Annual fee | Free for life |
| Minimum monthly spend | None |
| Cashback redemption | From AED 100 |
| Minimum salary | AED 5,000 |
Consider someone spending AED 1,500 monthly at eligible restaurants. At 5%, this would generate AED 75 in dining cashback, equivalent to AED 900 annually if the spending pattern remained unchanged.
The absence of an annual fee makes this easier to justify than a premium card requiring substantial spending to offset its charges.
Cashback can be redeemed through Mashreq’s banking channels once the minimum redemption balance is reached.
Our assessment: One of the most practical choices for regular restaurant spending, particularly for residents who want a straightforward no-annual-fee option.
3. HSBC Live+ Credit Card – Best for Dining, Fuel and Entertainment
HSBC Live+ offers a useful mixture of lifestyle and essential-spending rewards.
Eligible dining transactions earn 6%, fuel earns 5%, while supermarkets and entertainment spending earn 2%.
To qualify for these enhanced rates, cardholders must spend at least AED 3,000 during the relevant monthly statement cycle. Otherwise, the lower standard cashback rate applies.
| Feature | Details |
| Dining | 6% |
| Fuel | 5% |
| Groceries and entertainment | 2% |
| Other purchases | 0.5% |
| Enhanced cashback requirement | AED 3,000 monthly |
| Category caps | AED 200 per category grouping per statement cycle |
| Annual fee | AED 313.95 after first year, waivable |
| Minimum salary | AED 5,000 at approved employers; otherwise AED 12,500 |
HSBC currently waives the first-year annual fee and provides a subsequent waiver for qualifying annual expenditure of AED 12,000.
The card can therefore remain relatively affordable for residents already using it regularly.
For illustration, spending AED 1,000 on dining, AED 800 on fuel, AED 1,200 on groceries and AED 2,000 elsewhere could produce AED 134 in a qualifying month, assuming all transactions are eligible.
That works out to a potential AED 1,608 over 12 similar months before any fees.
Our assessment: Strong for mixed lifestyle spending and particularly attractive where customers qualify for the annual fee waiver.
4. Sharjah Islamic Bank Cashback Card – Best for Eligible Online Shopping
The Sharjah Islamic Bank (SIB) Cashback Card is particularly interesting for residents who frequently purchase goods online or use digital wallets.
Its headline offer is 10% cashback on qualifying online and digital-wallet transactions, subject to a monthly cap of AED 300.
However, the classification rules are critical.
Transactions involving supermarkets, education, government services, fuel, utilities, certain fast-food merchants and other designated categories are excluded from this enhanced rate.
| Feature | Details |
| Eligible online and wallet purchases | 10% |
| Maximum enhanced monthly cashback | AED 300 |
| Other qualifying international purchases | 2% |
| Eligible domestic retail | 1% |
| Certain excluded merchant categories | Lower earning rates |
| Annual fee | Free first year; AED 199 thereafter, waivable |
| Minimum salary | AED 5,000 with salary transfer; AED 8,000 without |
A customer making AED 3,000 in qualifying online purchases could potentially earn AED 300 cashback.
However, paying AED 3,000 for groceries using Apple Pay does not automatically mean the same reward applies because merchant-category exclusions still matter.
SIB waives the second-year annual fee when the previous year’s qualifying expenditure reaches AED 10,000.
Our assessment: One of the strongest specialised cards for eligible digital purchases, but its exclusions mean it should not be treated as a universal 10% cashback card.
5. Citi Cash Back Credit Card – Best for Consistent Cashback Across Categories
The Citi Cash Back Credit Card is designed for residents who prefer predictable rewards without monitoring several category-specific monthly limits.
Its structure includes 3% cashback on non-AED spending, 2% on groceries and 1% on other eligible purchases.
There is no minimum monthly spending requirement, and Citi advertises no general cashback cap beyond the available credit limit and applicable programme terms.
| Feature | Details |
| Non-AED spending | 3% |
| Groceries | 2% |
| Other eligible transactions | 1% |
| Minimum spend | None |
| General cashback cap | No fixed programme cap within the credit limit |
| First-year annual fee | Free |
| Subsequent fee | AED 300 plus VAT if annual waiver condition is not met |
| Annual fee waiver threshold | AED 9,000 annual spend |
| Minimum salary | AED 8,000 |
The main advantage is consistency.
A resident who spends money across different retailers does not need to rely entirely on a single reward category.
However, cashback on foreign-currency purchases should always be assessed after currency conversion fees and exchange-rate costs.
A nominal 3% reward does not necessarily mean a net 3% saving.
Our assessment: A versatile card for customers seeking straightforward rewards and relatively modest annual spending requirements.
6. FAB Cashback Credit Card – Best for Groceries, Dining and Fashion
First Abu Dhabi Bank’s Cashback Credit Card rewards several common household and lifestyle expenses.
Customers can receive 5% cashback on qualifying supermarkets, dining and fashion purchases.
Non-AED spending earns 3%, while most other eligible transactions earn 1%.
One important detail is that the enhanced categories each have their own monthly cashback cap.
| Feature | Details |
| Supermarkets | 5% |
| Dining | 5% |
| Fashion | 5% |
| International spending | 3% |
| Other eligible purchases | 1% |
| Individual 5% category cap | AED 150 monthly |
| Overall monthly cap | Up to AED 1,000 |
| Minimum spending condition | AED 3,000 in the preceding month |
| Annual fee | AED 300, with applicable VAT to be checked |
| Minimum salary | AED 5,000 |
For example, AED 3,000 in qualifying supermarket expenditure could reach the AED 150 monthly supermarket cap.
Spending another AED 1,000 in that same category would not increase the enhanced category reward.
FAB processes cashback through its rewards programme, meaning customers should check the redemption procedure rather than assuming automatic cash deposits.
Our assessment: A competitive option for families with a balanced mixture of grocery, dining and fashion expenses.
FAB
7. CBD Super Saver Credit Card – Best for High Household Bills
Commercial Bank of Dubai’s Super Saver Credit Card focuses on four essential expenditure categories.
The bank groups them under B.E.S.T.: Bills, Education, Supermarkets and Transport.
Qualifying spending can earn between 3% and 10% depending on total monthly card expenditure.
This makes the card attractive for families paying significant household expenses, but the highest rate requires a comparatively high spending level.
| Monthly Total Spending | Eligible B.E.S.T. Cashback Rate | Combined Monthly Cap |
| Below AED 3,000 | 0% | AED 0 |
| AED 3,000–9,999 | 3% | AED 300 |
| AED 10,000–19,999 | 5% | AED 400 |
| AED 20,000 or more | 10% | AED 600 |
The bank also imposes category-specific cashback limits, meaning even households spending AED 20,000 monthly may not achieve a 10% return across their entire bill.
For example, AED 2,000 of eligible supermarket spending within the highest tier would theoretically produce AED 200 at 10%, but a category cap of AED 150 would reduce the payable reward.
The card is free for the first year, with subsequent annual charges governed by the bank’s fee schedule.
The minimum advertised salary is AED 5,000.
Our assessment: Best suited to higher-spending families who can consistently qualify for the upper cashback tiers, rather than occasional card users.
8. Emirates Islamic Switch Cashback Card – Best for Flexible Lifestyle and Travel Rewards
The Emirates Islamic Switch Cashback Card provides Shariah-compliant cashback with a choice between Lifestyle and Travel reward categories.
This flexibility is particularly useful for residents whose spending changes throughout the year.
Under Lifestyle mode, eligible domestic fuel purchases earn 8%, while supermarkets, dining and education earn 4%.
Travel mode instead prioritises airlines, hotels and dining, each at 4%.
| Feature | Details |
| Lifestyle fuel cashback | 8% |
| Lifestyle groceries and dining | 4% |
| Lifestyle education | 4% |
| Travel-mode airlines and hotels | 4% |
| Fuel monthly cap | AED 100 |
| Other enhanced category caps | AED 200 each |
| Minimum monthly spend | AED 2,500 |
| Annual fee | Free first year; AED 299 plus VAT thereafter |
| Annual waiver threshold | AED 30,000 qualifying annual spending |
A resident who drives regularly may prefer Lifestyle mode, while someone booking a holiday might switch to Travel mode.
The bank permits customers to update their preferred category through its mobile application.
Importantly, the selected category determines the cashback calculations for the relevant calendar month, rather than applying both reward structures simultaneously.
Our assessment: A flexible Islamic cashback option for people whose expenses alternate between everyday essentials and travel.
Apply Now – Emirates Islamic Switch
9. Dubai Islamic Bank Consumer Cashback Platinum – Best for School Fees and Utilities
The Dubai Islamic Bank Consumer Cashback Platinum Card offers Shariah-compliant rewards across several practical spending categories.
Eligible purchases covering supermarkets, school fees, automobile servicing, telecommunications, utilities and fuel can earn 4% cashback.
The card is especially relevant for families with recurring education expenses.
| Feature | Details |
| Supermarkets | 4% |
| School fees | 4% |
| Automobile servicing | 4% |
| Fuel | 4% |
| Utilities and telecom | 4% |
| Overall monthly cashback cap | AED 1,000 |
| Minimum monthly spending | AED 4,000 |
| Annual fee | AED 249 plus VAT; first-year offer may apply |
| Minimum salary | AED 15,000 |
An important update took effect on 10 October 2026: DIB reduced the monthly cashback cap for supermarkets and school fees to AED 300 for each category.
Customers should also note that payments made through certain bank-operated bill-payment platforms may be excluded.
The AED 4,000 minimum monthly retail spend is essential. Without meeting it, customers will not qualify for cashback under the published programme conditions.
Our assessment: Strong for higher-income families paying school fees and household bills, provided they meet the salary and spending requirements.
Apply Now – DIB Consumer Cashback Platinum
10. Dubai First Cashback Credit Card – Best for Everyday Essentials
The Dubai First Cashback Credit Card rewards groceries, restaurants and fuel purchases at the same enhanced rate.
Eligible spending in these three categories receives 5% cashback, with a monthly limit of AED 150 per category.
Other eligible domestic and international purchases generally earn 0.5%.
| Feature | Details |
| Supermarkets | 5% |
| Dining | 5% |
| Fuel | 5% |
| Other eligible purchases | 0.5% |
| Monthly enhanced cap | AED 150 per category |
| First-year annual fee | Free under the current offer |
| Subsequent annual fee | Subject to published fee schedule |
| Minimum salary | AED 5,000 |
A household spending AED 2,000 on groceries and AED 1,000 on dining could potentially earn AED 150 from those two categories in one month, before considering other purchases.
The card also offers selected cinema, food-delivery and travel benefits.
However, these additional offers should be treated separately from guaranteed cashback because availability and redemption rules may change.
Our assessment: A practical choice for customers whose largest expenses are groceries, restaurants and fuel, without complicated reward-category switching.
Apply Now – Dubai First Cashback
11. Wio Credit – Best for Digital Banking and Broad Cashback
Wio Credit offers a digital-first alternative to traditional cashback cards.
Instead of focusing exclusively on particular merchants, the bank advertises up to 2% cashback on eligible credit-card spending.
Wio Credit operates within the broader Wio Personal banking ecosystem, which offers different account plans and eligibility conditions.
| Feature | Details |
| Advertised credit cashback | Up to 2% |
| Monthly cashback cap | AED 2,500 |
| Banking model | Digital-first |
| Account requirement | Applicable Wio Personal account and qualifying plan |
| Account charges | Depend on plan and waiver conditions |
| Credit approval | Subject to bank assessment |
One important distinction is that the advertised 2% rate is not necessarily available under every account plan.
Wio identifies the qualifying Salary, Family and Plus plans in its current product information.
For the Salary plan, the ordinary minimum salary-transfer requirement is AED 15,000, with a lower threshold for employees of eligible partner companies.
Customers should therefore calculate the total value after any banking-plan charges.
Our assessment: Especially appealing for digitally confident customers who prefer broad-based rewards and already qualify for the relevant Wio banking plan.
12. Liv Cashback Credit Card – Best for Simple Spending-Based Rewards
Liv Cashback offers a relatively straightforward approach to earning rewards across everyday spending.
Unlike cards that heavily emphasise dining or fuel, Liv adjusts the cashback rate according to total monthly expenditure.
Under Liv’s published rewards structure, the standard Cashback Card provides 0.75%, 1.5% or 2% depending on the monthly spending tier.
| Monthly Card Spending | Cashback Rate |
| Below AED 5,000 | 0.75% |
| AED 5,000–9,999 | 1.5% |
| AED 10,000 or more | 2% |
The standard Liv Cashback Card has no joining or annual fee and a monthly cashback cap of AED 750.
A customer spending AED 6,000 in eligible categories could earn AED 90 in a qualifying month at 1.5%.
Those spending AED 10,000 monthly could theoretically generate AED 200 at 2%, before considering transactions that receive reduced rates.
Liv also offers a separate Cashback+ product with higher earning potential and additional charges. It should not be confused with the standard free-for-life card.
Our assessment: Suitable for residents who want rewards without managing numerous bonus categories.
13. RAKBANK Titanium Credit Card – Best for Dining and Entertainment
RAKBANK Titanium combines enhanced cashback on everyday shopping with entertainment-related benefits.
Customers can earn up to 5% on eligible supermarket and dining purchases.
Selected cinema and streaming transactions may qualify for substantially higher promotional rates, subject to the relevant limits and conditions.
| Feature | Details |
| Supermarkets | Up to 5% |
| Dining | Up to 5% |
| Cinema and selected streaming | Up to 50% |
| Standard eligible spending | Up to 2% |
| Combined cashback cap | Up to AED 600 monthly |
| Annual fee | Free for life |
| Minimum salary | AED 8,000 |
The entertainment rates should not be interpreted as 50% cashback on every subscription or cinema purchase.
Minimum spending conditions and transaction-specific caps are important.
The absence of an annual membership fee makes RAKBANK Titanium an option worth considering for residents who regularly spend on groceries and dining.
Our assessment: Particularly useful where entertainment benefits complement an existing pattern of supermarket and restaurant spending.
14. Al Hilal Bank Cashback Credit Card – Best for Personalised Islamic Cashback
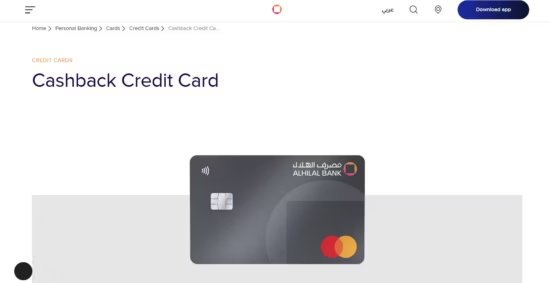
Al Hilal Bank allows customers to choose two preferred spending categories for enhanced cashback.
Available categories include groceries, education, fuel, dining and eligible international spending.
The card advertises up to 5% on the selected categories, while other eligible retail transactions generally earn 1%.
| Feature | Details |
| Preferred categories | Choose two |
| Maximum selected-category cashback | Up to 5% |
| Other eligible retail spending | 1% |
| Overall monthly cashback cap | AED 500 |
| Preferred-category cap | AED 250 per category |
| Annual fee | Free for life |
| Typical minimum salary | AED 5,000 |
The enhanced rate depends on the programme’s qualifying spending conditions, so customers should not assume every selected-category transaction automatically earns 5%.
A family whose largest spending categories are groceries and education could select those two areas, rather than accepting a fixed reward structure that may not match its expenses.
The card is also Shariah-compliant.
Our assessment: A flexible choice for residents with two clear spending priorities who prefer Islamic banking and no annual membership fee.
15. ADCB Talabat Credit Card – Best for Frequent Food Delivery Orders
The ADCB Talabat Credit Card advertises one of the highest cashback percentages in the UAE market.
Cardholders can receive 35% back on eligible Talabat purchases.
However, the reward is issued as Talabat credit rather than unrestricted cash.
The enhanced reward applies only to the first 10 qualifying orders each month, with a maximum of AED 35 per order.
| Feature | Details |
| Talabat orders | 35% as Talabat credit |
| Maximum reward per order | AED 35 |
| Qualifying orders | First 10 monthly |
| Maximum enhanced monthly reward | AED 350 |
| Minimum monthly retail spend | AED 2,500 |
| Other eligible retail spending | Up to 1.25% as Talabat credit |
| Annual fee | Free for life |
| Minimum salary | AED 5,000 or qualifying credit eligibility |
Consider someone making 10 qualifying Talabat orders worth AED 100 each.
At 35%, these orders could generate AED 350 in Talabat credit, provided the overall monthly spending requirement is satisfied.
That represents a sizeable reward, but its value depends on the customer continuing to use the Talabat platform.
The card is therefore less versatile than a product offering cashback that can be redeemed against any credit-card statement.
Our assessment: Potentially excellent for regular Talabat customers, but not a substitute for flexible cash rewards.
Which Cashback Credit Card in UAE Is Best for Different Spending Habits?
There is no universally best cashback credit card because individuals have different spending priorities.
| Spending Priority | Cards Worth Comparing | Main Consideration |
| Dining | HSBC Live+, Mashreq, ADCB 365 | Dining rate, caps and spend floor |
| Groceries | FAB Cashback, ADCB 365, Dubai First | Grocery limits and annual fees |
| Online shopping | SIB Cashback | Merchant exclusions |
| Fuel | Emirates Islamic Switch, HSBC Live+, ADCB 365 | Category caps |
| School fees | DIB Consumer Cashback Platinum, CBD Super Saver | Salary and monthly spend requirements |
| General spending | Citi Cash Back, Liv Cashback, Wio Credit | Net effective cashback |
| Food delivery | ADCB Talabat | Platform-credit restrictions |
| Shariah-compliant rewards | SIB, DIB, Al Hilal, Emirates Islamic | Financing terms and cashback eligibility |
For many UAE residents, a combination of one primary card and one specialist card may deliver better results than relying exclusively on a product with the highest headline percentage.
However, additional cards also increase repayment responsibilities and require closer monitoring.
How Much Cashback Can You Actually Earn in a Year?
To understand the financial value of a card, it is helpful to separate theoretical cashback from realistic rewards.
The following examples demonstrate different earning structures. They are illustrative calculations, not personalised earnings forecasts.
| Example | Eligible Monthly Spending | Assumed Cashback | Gross Annual Cashback |
| Flat-rate cashback | AED 3,000 | 1% | AED 360 |
| Broad-rate cashback | AED 5,000 | 2% | AED 1,200 |
| Category cashback | AED 2,000 | 5% | AED 1,200 |
| Enhanced cashback | AED 3,000 | 10% | AED 3,600 before caps |
| Capped cashback | AED 3,000 | 10%, capped at AED 150 monthly | AED 1,800 |
The fourth and fifth examples show why monthly limits matter.
Two cards both advertising 10% cashback could produce very different annual results.
The most useful financial measure is:
Net annual cashback = Eligible cashback earned − annual fees − additional costs attributable to the card.
For instance, if a card produces AED 1,200 in annual cashback but charges AED 420 in membership fees, its net benefit is AED 780 before other costs.
If another card produces AED 900 in cashback without an annual fee, that second product would offer the stronger net financial return.
This becomes especially important when comparing premium cashback credit cards with free-for-life alternatives.
What Should You Check Before Applying for a Cashback Credit Card in UAE?
Cashback rates are only one part of the application decision.
The following conditions can significantly affect the financial outcome.
1. Monthly minimum spending
Some cards require AED 2,500, AED 3,000, AED 4,000 or AED 5,000 in monthly purchases before enhanced cashback becomes available.
A card requiring AED 5,000 in spending offers little reward value to someone who consistently spends AED 2,000.
2. Cashback limits
Banks may impose separate monthly limits for groceries, dining, fuel or online shopping.
For example, a 5% category offering a maximum of AED 150 cashback reaches that limit after AED 3,000 in eligible spending.
3. Annual membership charges
Some cards waive charges in the first year but begin charging fees in the second year.
Where a bank offers an annual fee waiver, the required spending threshold should be checked carefully.
4. Merchant category codes
Cashback eligibility is often determined by merchant category codes assigned through payment networks.
This explains why an online supermarket purchase may not earn the same enhanced cashback as an online fashion purchase, even when both transactions are completed digitally.
5. Foreign transaction charges
International cashback should be evaluated after foreign exchange markups and applicable fees.
A card earning 3% cashback abroad may deliver a much smaller net saving after conversion costs.
6. Cashback redemption
Some banks provide statement credits, while others issue rewards points, merchant credits or app-specific balances.
These are not necessarily interchangeable.
7. Interest and repayment charges
A card generating AED 100 in monthly cashback can quickly become expensive if the outstanding balance attracts finance charges.
Jamal Alvi, identified as Abu Dhabi Islamic Bank’s chief credit officer in a published financial advice panel, offered the practical warning: “You should spend only as much every month that you can pay in full.”
That principle remains fundamental when evaluating reward cards.
Readers can also explore ways to maximise credit card rewards in the UAE while maintaining disciplined repayment habits.
How Do Cashback Credit Cards Affect Your Credit Score in UAE?
Applying for a cashback credit card involves more than checking salary eligibility.
Banks also consider the applicant’s overall creditworthiness, existing borrowing commitments and repayment history.
The Al Etihad Credit Bureau (AECB) maintains credit information used by lenders to assess applications.
Regular on-time repayments and responsible credit utilisation can support a healthier borrowing profile, while missed payments and excessive outstanding balances may have negative consequences.
Before applying for several cards, residents should understand how to check their credit score in the UAE.
This is particularly important for applicants planning to apply for a mortgage, personal loan or vehicle finance in the future.
A high cashback percentage does not justify taking on credit obligations that cannot be repaid comfortably.
Are Cashback Credit Cards Worth It for UAE Residents?
Cashback cards can be financially worthwhile when used for purchases that would have been made anyway.
The strongest opportunities usually arise where spending is predictable, eligible for rewards and consistently repaid in full.
A family spending AED 8,000 monthly on groceries, dining, petrol and other essentials may benefit from a category-focused cashback card.
Someone spending only AED 1,500 monthly may find a no-annual-fee option more practical.
Likewise, a resident who frequently shops on a particular delivery platform may obtain additional value from a co-branded card, provided the rewards are regularly redeemed.
However, the headline return should never be treated as a guaranteed saving.
Credit-card agreements, interest rates and disputed fees require attention. A recent UAE credit card debt dispute illustrates why customers should understand the written contractual terms and keep appropriate records of charges and repayments.
The practical objective is not to obtain the card with the largest advertised reward. It is to choose one that creates a positive net benefit without encouraging additional borrowing or unnecessary spending.
How to Apply for the Best Cashback Credit Cards in UAE?
Most major UAE banks provide an online application process, although some products require customers to complete the application through an official mobile banking app.
Applicants will typically need valid identification, evidence of UAE residency, income documentation and information about existing financial commitments.
Depending on the bank and employment circumstances, documents may include an Emirates ID, passport, residence visa, salary certificate and recent bank statements.
Self-employed applicants may need additional financial records.
Approval is not guaranteed simply because the applicant meets the stated minimum monthly salary. Banks assess credit history, liabilities and internal lending criteria.
Before submitting an application, review the bank’s current Key Facts Statement, cashback terms, schedule of charges and repayment conditions.
FAQs
Which is the best cashback credit card in UAE for 2026?
ADCB 365, Mashreq Cashback, HSBC Live+, SIB Cashback and Citi Cash Back are strong candidates for different spending patterns. The best choice depends on monthly expenditure, category eligibility, annual fees and cashback caps.
Which UAE credit card offers 10% cashback?
SIB Cashback offers up to 10% on eligible online and wallet purchases, while CBD Super Saver can offer 10% in selected categories at its highest spending tier. Both impose conditions and reward limits.
Which cashback credit card in UAE is free for life?
Mashreq Cashback, Liv Cashback, RAKBANK Titanium, Al Hilal Cashback and ADCB Talabat are among the products advertising no annual membership fee.
Can I get a cashback credit card with a salary of AED 5,000?
Yes. Several banks advertise credit cards for customers earning AED 5,000 monthly, although employment details, liabilities and creditworthiness will determine whether an application is approved.
Which UAE cashback card is best for groceries?
FAB Cashback, Dubai First Cashback and ADCB 365 are worth comparing. FAB and Dubai First advertise 5% on eligible groceries, while ADCB currently offers 3% with a broader selection of cashback categories.
Can I earn cashback on school fees in UAE?
Yes. Cards such as DIB Consumer Cashback Platinum and CBD Super Saver provide rewards for qualifying education spending, subject to minimum spending requirements and monthly cashback limits.
Are cashback credit cards better than rewards cards?
Cashback cards offer relatively transparent monetary value. Rewards cards may be more attractive when customers consistently redeem points or airline miles at favourable rates.
Do cashback rewards expire?
They can. Expiry periods and forfeiture conditions vary by bank. Customers should review their programme terms and redeem eligible rewards before closing a card.
Can expats apply for cashback credit cards in UAE?
Yes. Many banks accept applications from eligible expatriate residents who meet identification, salary and lending requirements.